12 common mistakes buyers make when applying for a home loan (and how to avoid them)
Getting approved for a mortgage is a key step in the journey towards purchasing a home. However, preparing your home loan application can feel like an overwhelming task — particularly as some lenders require copious amounts of paperwork.
As more lenders tighten up their policies in light of the COVID-19 pandemic, every aspect of your application needs to be error-free if you want to secure a fast approval. Making mistakes in your application could lead to significant delays in the home loan approval process — or worse yet, reduce your chances of getting approved down to zero.
So what are the common mistakes that borrowers make when applying for a home loan, and how can you avoid them? We look at 12 of the big ones here.
1. Bidding at auction without getting pre-approved
Before bidding at an auction, you need to organise a home loan pre-approval (or conditional approval) with your lender. Not doing so is incredibly risky, and puts you in a precarious situation should you be the successful bidder.
If you’re the winning bidder at a property auction, you’re buying the property unconditionally. This means you need to sign a contract of sale after the auction and pay the deposit on the spot, which typically ranges between 10% to 20% of the purchase price. If you haven’t been approved for a home loan, you may need to pay hefty penalties and could even lose your deposit.
How to avoid it: organise your home loan finance at least 2-3 weeks in advance. If you give yourself enough lead time between your application and the auction, you may be able to secure formal approval. However, conditional approval is typically enough to start bidding.
2. Not knowing your credit history
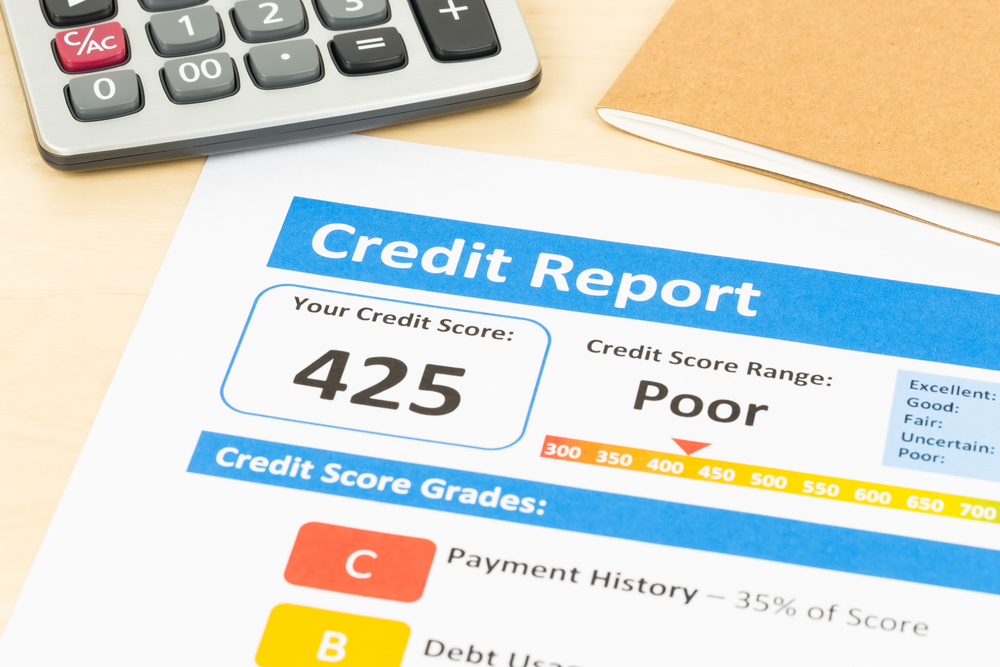
Your credit history is one of the first things a lender will look at when assessing your application.
Having a poor credit history — such as deferring or defaulting on a loan, or missing repayments — means you’re more of a risk in the lender’s eyes. Your lender may restrict the amount you are able to borrow or reject your application altogether.
How to avoid it: request a copy of your credit report. You can obtain a free credit report from a reputable online credit score provider, such as Equifax, CheckYourCredit (illion), or Experian. If you are a Rateseeker client, rest easy — our mortgage brokers will organise this report on your behalf before submitting your application.
In addition, if you have something negative listed in your credit history, it’s best to work with your mortgage broker to find the best solution.
3. Not accurately reporting your income and expenses
Lenders use these two factors to assess your borrowing power, and determine whether you are able to repay your mortgage.
Lenders have highly sophisticated systems for detecting fraud or inconsistencies in your application, from cross-checking your tax returns and bank statements to sharing data with other financial institutions.
If you overestimate your household income or underestimate your expenses, this could result in your application being denied — in the best case. In the worst-case scenario, a lender could even file a case against you, which could lead to hefty penalties.
How to avoid it: be as accurate and diligent as possible when detailing your income and expenses on your application. If you do make a mistake (and it happens), notify your lender straight away to avoid any delays or risks to your application.
4. Not doing your research on different home loan rates
Many buyers default to applying for a home loan with their existing bank because it feels easy and straightforward. However, doing so could mean you’re not getting the best interest rate on your home loan.
While the difference between an interest rate of 3.5% p.a. and 3.4% p.a. might not seem like a lot, this can add up to tens of thousands in the long run. That’s enough money for a new car, a family holiday, or renovations on your existing property.
To find out how much you could be saving on your home loan, use our home loan comparison calculator.
How to avoid it: do your research, or work with a trusted broker like the team at Rateseeker. Our team has access to all the latest industry home loan rates, as well as exclusive products for clients. This means they can assist in finding the sharpest home loan rate for you.
5. Applying for a home loan based solely on the interest rate
While it’s important to do your research into different home loan options, you also need to keep in mind that not every amazing home loan interest rate is going to apply to you.
Lenders advertise the lowest rate possible to appeal to potential borrowers. However, the rate might only be applicable for people with a low loan-to-value ratio (LVR) or only applicable for certain home loan mortgage products.
How to avoid it: read the fine print carefully. Every lender needs to disclose all the terms and conditions of the loan, either on the product page, in a downloadable fact sheet or in their brochure.
Alternatively, work with a mortgage broker. Your broker understands the ins and outs of different lender policies and can provide tailored advice on the best home loan rate for your situation.
If you apply without reading the fine print, you might end up with a mortgage you aren’t able to service — or getting your application rejected altogether. Which brings us to the next point…
6. Submitting too many home loan applications
Every time you file an application with a lender, it goes on your credit file. Even if you don’t end up taking out that mortgage, a lender will notice these applications in your credit history. They may assume that you were rejected for those loans and deny your application — creating a vicious cycle.
How to avoid it: only apply for a home loan when you’re ready to commit. There are plenty of calculators available for you to work out your borrowing power without needing to submit an application, such as Rateseeker’s borrowing power calculator.
7. Missing loan repayments
Lenders want to take on good debt that they believe they will get back. As such, missing a few repayments on any loan, including credit cards and mortgage, could drastically affect your ability to secure a home loan, as well as your borrowing power.
Missing one repayment three years ago likely won’t have a significant impact. However, missing multiple payments, especially in a row, or having an overdrawn bank account could result in a lender declining your application. This could even extend to your water rates, electricity rates, phone bills and more.
How to avoid it: stay up-to-date with your current repayments. If you’ve missed an instalment, pay it as soon as possible and confirm this with your lender before or during your application.
If you’ve missed a few payments, it’s best to work with a mortgage broker to find the best solution for your financial situation. Get in touch with Rateseeker today to find out how we can help.
8. Not structuring your savings correctly
Having savings looks great on your application. A lender wants to see that you are responsible with your finances and have enough saved up to pay your deposit. However, lenders and Lenders Mortgage Insurance (LMI) providers also want to see that your deposit has been ‘genuinely saved’ — that is, saved over a long period of time and without being touched.
Constantly making withdrawals from your savings may raise some red flags in the lender and LMI providers’ eyes. The same goes for any large sums of money that suddenly appear in your savings account.
How to avoid it: open a separate bank account or a separate savings account. Put your home loan deposit in there and leave it untouched for at least 3 months.
9. Applying for a home loan during probation or significant life changes
In a lender’s eyes, the ideal borrower has a stable financial situation with no unexpected expenses or life changes coming up. As such, you need to demonstrate to your lender that you have a steady employment and home situation.
If you are still in the probationary period with your employer or have switched careers, a lender may be less likely to approve your loan application — or they might approve you for a lower amount. The same goes for any significant recent purchases, such as a new car, and any recent debt that you may have accumulated.
How to avoid it: wait until you’re out of your probationary period, or until you’re at least 6-12 months into your new career. Try to also avoid making any big purchases during this time frame, to demonstrate that you are responsible with your money and don’t have any big liabilities hanging over your head.
This is when speaking to a mortgage broker can be beneficial, as they can advise you on timelines for your application. For example, it may not be necessary to wait 6-12 months if you worked in the same industry or don’t have an employment gap.
10. Having high credit card limits
Even if you don’t use your credit card often, having a high credit limit could reduce the amount of money you can borrow. A lender will factor in a portion of your credit limit as a liability on your home loan, which ultimately could take tens or hundreds of thousands off your borrowing potential.
For example, someone with a $15,000 credit limit and someone with a $35,000 credit limit may have a different maximum borrowing capacity, even if they have the same deposit amount and income amount. This is because lenders will apply a rate of 3.8% on the credit card limit as an additional expense, regardless of whether you use your credit card.
How to avoid it: contact your lender and reduce your credit limit as much as possible before applying for a home loan. This will have a significant impact on your maximum borrowing potential.
11. Making a large deposit into your savings
This one may seem counterintuitive. After all, the more you have in your savings account, the better it looks to lenders, right?
Not always.
In the lead up to applying for a home loan, you’ll need to clearly document your expenses. Lenders look at this when making a decision, and will likely be suspicious of any large deposits or withdrawals – even if it was done with the best of intentions.
How to avoid it: try to steadily contribute to your savings, and record every transaction. If you have made a significant deposit into your savings, make sure you have a clear reason for the sudden increase.
It’s best to work with your mortgage broker to explain any large movements in your bank accounts. They will be able to communicate it in a way that looks favourable in a lender’s eyes.
12. Submitting an application with errors
Last but not least, one of the most common mistakes borrowers make when submitting a home loan application is just that: making mistakes.
While typos happen every now and then when doing paperwork, it’s critical to try and minimise the number of errors in your application. A home loan application that’s riddled with errors tarnishes your credibility as a borrower and makes a lender more hesitant to approve you for your loan. This could lead to delays in your application, as the lender will come back to you to clarify inconsistent information. Worse yet, your application could even be denied or flagged as fraudulent.
How to avoid it: be diligent and organised with your paperwork, and always double-check your application before submitting it to your lender.
Applying for a home loan can be a complicated process, particularly during the COVID-19 pandemic. A mortgage broker can help you navigate changing policies, weed out any inconsistencies in your paperwork, and recommend the best home loan for you.
At Rateseeker, we have access to the latest lender policies and home loan products. Our team will help you seek the sharpest rate and put you in the best position possible to get approved on your home loan. Contact us today for an obligation-free consultation.
** General Advice Warning
The information provided on this website is general in nature only and it does not take into account your personal needs or circumstances into consideration. Before acting on any advice, you should consider whether the information is appropriate to your needs and where appropriate, seek professional advice in relation to legal, financial, taxation, mortgage or other advice.